
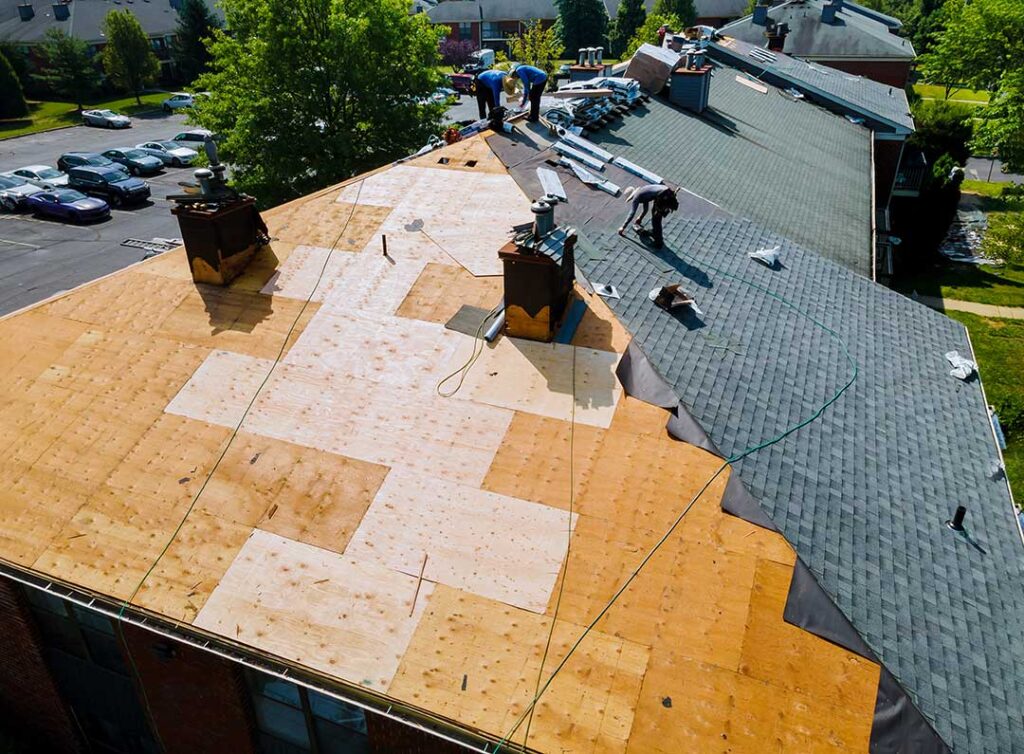
A roof claim is not automatically covered simply because the roof is leaking or needs replacement. Homeowner’s insurance generally responds to sudden damage caused by a covered event, while age, normal wear, poor maintenance, and long-term deterioration are usually treated differently.
For households in Canastota, NY, understanding that distinction can make it easier to document storm damage, review a policy, and avoid unpleasant surprises during a claim.
What roof damage does homeowner’s insurance usually cover?
Insurance commonly covers sudden roof damage caused by a listed event, or “peril,” such as wind, hail, lightning, fire, or the weight of certain storm-related debris. The exact wording depends on the policy.
Examples may include:
- Shingles torn away by strong wind
- A tree limb damaging the roof during a storm
- Hail strikes that crack or bruise roofing materials
- Fire damage
- Water entering through a newly storm-damaged area
Coverage usually depends on proving that the event caused the damage. A roof that has been gradually allowing water into the attic for several seasons may be viewed differently from a roof punctured by a falling branch during a documented storm.
A policy may also cover interior damage resulting from a covered roof loss. For example, if wind damages the roof and rain then damages ceilings or walls, both the roof and related interior damage may be considered. The policy’s exclusions, limits, and deductible still apply.
Is an old or worn-out roof covered?
Usually, not for the cost of replacing the roof solely because it has reached the end of its useful life. Insurance is designed primarily for unexpected losses, not routine replacement caused by age or deferred maintenance.
Insurers may inspect a roof’s:
- Approximate age
- General condition
- Missing, cracked, curled, or deteriorated shingles
- Previous repairs
- Evidence of leaks or repeated water entry
- Ventilation, flashing, and other components
A roof can be old and still have a covered storm loss. However, the insurer may separate pre-existing deterioration from the newer damage. For instance, wind may remove several shingles from an aging roof, but the payment may not include replacement of undamaged areas merely because the roof is old.
The National Association of Insurance Commissioners notes that some policies provide only actual cash value coverage for roofs over a certain age or in poor condition. That means depreciation may be deducted before payment is calculated. ([content.naic.org](https://content.naic.org/sites/default/files/committee_related_documents/Regulator%2520Resources%2520for%2520Consumers%2520on%2520Personal%2520Lines%2520Pricing%2520and%2520Underwriting_1.pdf?utm_source=openai))
What is the difference between replacement cost and actual cash value?
The difference can substantially affect what a homeowner receives.
Replacement cost value generally refers to the cost to repair or replace damaged property with materials of like kind and quality, without subtracting depreciation. Some policies pay an initial amount based on actual cash value and release the remaining replacement-cost amount after the work is completed and documented.
Actual cash value is generally the replacement cost minus depreciation for age, condition, and expected useful life.
For example, if storm damage requires $12,000 in roofing work but the insurer calculates $4,000 in depreciation, the actual cash value may be $8,000 before the deductible. A replacement-cost policy may allow recovery of some or all of the depreciation after qualifying repairs, while an actual-cash-value policy may not.
The declarations page and policy endorsements should be checked for roof-specific limitations. The type of coverage can vary even among policies that appear similar.
Does insurance pay for the entire roof?
Not necessarily. The insurer may pay only for the portion damaged by a covered event, depending on the policy and the extent to which matching materials are addressed.
Roofing materials can change over time. A discontinued shingle may make a small repair difficult to match, but that does not automatically mean the entire roof is covered. The policy may contain provisions addressing matching, ordinance or law requirements, or the method used to calculate a partial repair.
A roof inspection should distinguish between:
- Direct storm damage
- Existing wear and deterioration
- Damage caused by earlier, undocumented events
- Installation defects
- Damage from animals, insects, or lack of maintenance
Clear photographs and written observations can help separate these conditions.
What roof problems are commonly excluded?
Common exclusions or limitations may involve:
- Normal aging and wear
- Rot, corrosion, or deterioration
- Defective workmanship or materials
- Long-term seepage
- Mold or rot resulting from an unresolved leak
- Damage caused by neglect
- Flooding or surface water
- Certain types of ice, snow, or water-related losses
- Damage caused by pests or animals
Coverage for water backup or sewer-related damage may require a separate endorsement. Standard homeowner’s insurance also generally does not cover flood damage; New York’s Department of Financial Services explains that flood or mudslide coverage is typically obtained through a separate policy. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/help_for_homeowners/insurance/basic_coverage?utm_source=openai))
Heavy rain is not always the same as flooding. Water entering through a storm-damaged roof may be evaluated differently from water rising from the ground or entering through surface drainage.
How do seasonal conditions affect roof claims?
The seasonal cycle in Canastota can place repeated stress on roofing systems. Freeze-thaw changes, wind, ice, heavy snow, falling branches, and spring rainfall can expose weak flashing, aging sealants, and previously repaired areas.
Winter damage is not automatically covered just because snow or ice is present. The policy may consider whether the loss resulted from a covered event, a structural failure, poor maintenance, or a known condition that was not corrected.
Homeowners should be cautious about walking on an icy or snow-covered roof. From ground level, useful documentation may include:
- Photographs of fallen branches or visible roof openings
- Pictures of damaged siding, gutters, or flashing
- The date and approximate time of the storm
- Interior photographs showing staining or active water entry
- Temporary repair receipts
- Notes about when the leak was first observed
Do not make permanent repairs before the insurer has a reasonable opportunity to inspect, unless delaying action would allow additional damage. Temporary steps to keep out rain or prevent unsafe conditions are generally different from replacing the roof before documentation is complete.
What should happen after suspected storm damage?
First, protect people from hazards and limit additional damage when reasonably safe. Then document the condition and notify the insurer according to the policy’s reporting requirements.
The insurer may send an adjuster to inspect the damage and prepare an estimate. New York’s Department of Financial Services states that policyholders may also obtain their own repair estimate for comparison, while the policyholder remains responsible for supporting the claimed loss with documentation. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
Useful records may include:
- The policy declarations page
- Photos taken before temporary repairs
- Photos of damaged roofing and interior areas
- Weather records or storm dates
- Maintenance and repair records
- Invoices for emergency protection
- A list of damaged personal property
- Written communication with the insurer
A claim should describe observed facts rather than guess at the cause. “Three shingles were found in the yard after the windstorm” is more useful than asserting that the entire roof must be replaced without supporting evidence.
What if the claim is denied or the payment seems too low?
Ask for the decision and the policy language supporting it in writing. A denial should identify the relevant exclusion, limitation, or condition rather than simply stating that the damage is not covered.
Compare the insurer’s estimate with the actual observed damage. Differences may result from omitted roof sections, missing interior repairs, depreciation, code-related work, or the deductible.
In New York, homeowner policies contain an appraisal provision for certain disputes about the amount of loss. If a disagreement cannot be resolved, the state Department of Financial Services also identifies complaint procedures and explains the roles of licensed public adjusters and attorneys. ([dfs.ny.gov](https://www.dfs.ny.gov/consumers/disaster_flood?utm_source=openai))
The most useful insurance review is done before a loss occurs. Check the roof’s age, the policy’s roof settlement method, deductibles, exclusions, coverage limits, and any endorsements. A few minutes spent reading the declarations page can reveal whether the policy is based on replacement cost, actual cash value, or a combination of both.
